 TechAnalyzer Pro
SimilarWeb Ltd SMWB
Stock research in plain language · As of Oct 23, 2026 · updated once a week, after the trading week closes
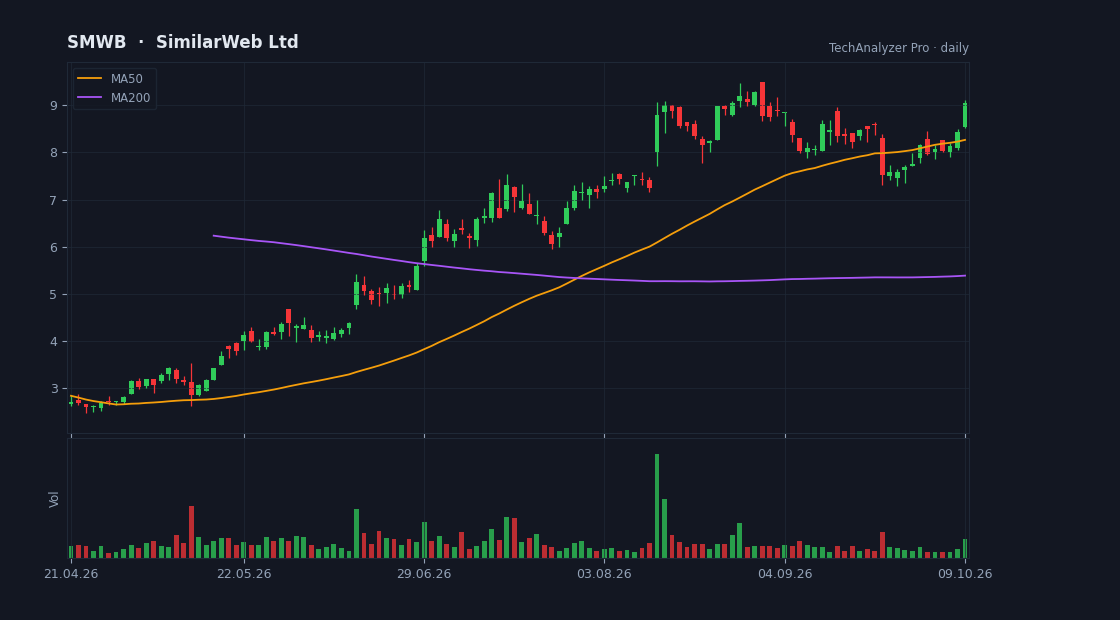
Daily candles, 50 and 200-day averages and volume · updated every trading day · click to open the live chart
What the company does
SimilarWeb Ltd is a small-cap company in the Technology sector (Software - Application), with a market value of $781M, based in the USA.
It employs about 1,000 people and has been listed since May 12, 2021.
Similarweb Ltd. provides digital data and analytics for power critical business decisions in the United States, Europe, the Asia Pacific, the United Kingdom, Israel, and internationally. The company offers web intelligence solutions for its customers to benchmark performance against competitors, analyze trends in the market, conduct deeper research into specific companies, and analyze audience behavior; and solutions for its customers to understand their competitors' digital acquisition strategies on various marketing channel, and optimize their own strategies.
Cheap or expensive? relatively cheap
The company is loss-making, so it has no P/E — we compare on price-to-sales instead.
Its price-to-sales (P/S) is 2.6 versus 6.6 for the median of the Technology sector in our universe (65 companies) — relatively cheap.
Revenue is growing 9% versus the same quarter last year.
The average analyst price target is 10.83, 23% above the current price (their view, not ours).
The stock sits at 91% of its one-year range (0% = the low, 100% = the high).
The risks
- • The company is loss-making.
- • The stock is more volatile than average (beta 1.3) — big daily moves both ways.
- • Low trading volume — hard to buy or sell size without moving the price.
Strengths
- ✅ Generates free cash flow — profit becomes cash in the bank.
- ✅ More cash than debt.
- ✅ Most analysts rate it buy (5 vs 0).
What changed this week
Over the past week the stock rose 0.3% (for comparison: S&P 500 -1.0%, sector ETF XLK -3.6%).
This week's news
- Meta Stock Falls. Earnings Show Just How Much Future Growth Will Cost. finance.yahoo.com · 2026-10-22
What the article says
Mounting expenses are weighing on Meta Platform’s profitability and the company admits scaling Muse is going to costly. Continue Reading source ↗
What changed since last week
No material change: same valuation verdict, same risk flags, price moved less than 3%.
A description of facts from the filings and the market — not investment advice or a recommendation. "Cheap" and "expensive" are always relative to the comparison group. Educational information only — not investment advice. Not a registered investment adviser or broker-dealer.