 TechAnalyzer Pro
Microsoft Corporation MSFT
Stock research in plain language · As of Oct 25, 2026 · updated once a week, after the trading week closes
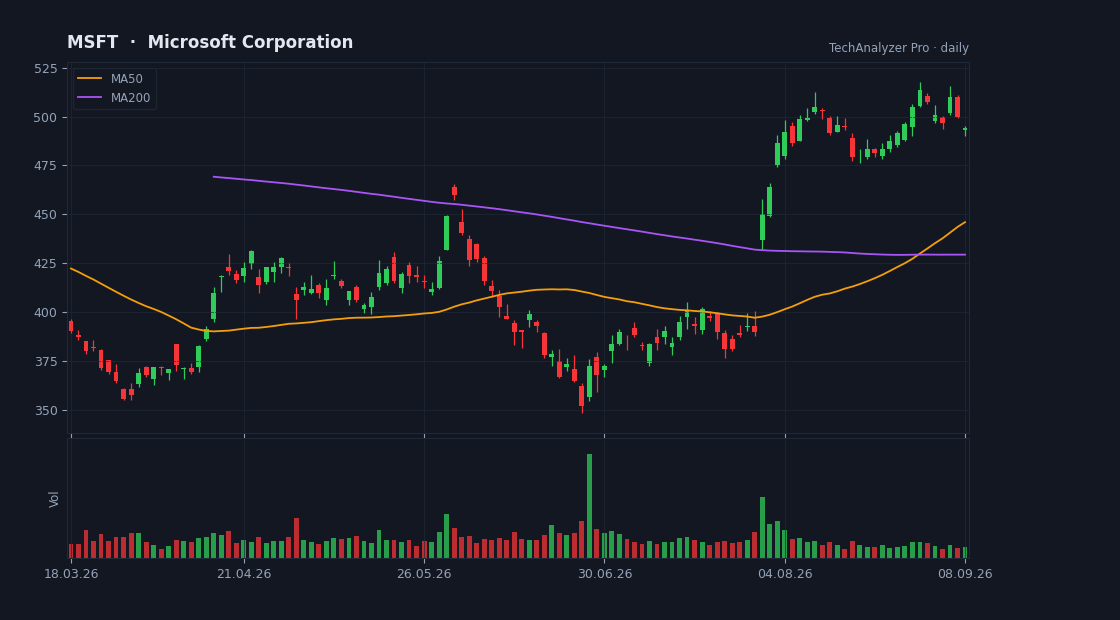
Daily candles, 50 and 200-day averages and volume · updated every trading day · click to open the live chart
The bottom line
Microsoft trades at about a $3.9 trillion market cap, with 17.7% revenue growth and $35.8 billion net income last quarter, so the stock moves on cloud and AI momentum versus the scale of its infrastructure spending. This week's articles show both sides: a strong balance sheet and positive free cash flow, against $140.6 billion of capital spending and questions about how much AI compute is actually live and who the paying customers are. At 29.2x earnings versus a 35x peer median, the price assumes growth continues and the buildout pays off. The central tension for a holder is huge spending today against AI revenue that must arrive later, with the October 28 report the next checkpoint.
An explanation of the mechanics from the facts on this page, not advice.
What the company does
Microsoft Corporation is a mega-cap company in the Technology sector (Software - Infrastructure), with a market value of $3.89T, based in the USA.
It employs about 223,000 people and has been listed since Mar 13, 1986.
Microsoft Corporation, a technology company, develops and supports a portfolio of technology solutions for individuals and businesses worldwide. Its products include operating systems, server applications, business solution applications, software development tools, desktop and server management tools, and video games; and devices, such as PCs, tablets, gaming and entertainment consoles, other intelligent devices, and related accessories. The company's Productivity and Business Processes segment offers Microsoft 365 Commercial, Enterprise Mobility + Security, Power BI, Exchange, SharePoint, Microsoft Teams, Microsoft 365 Security and Compliance, Microsoft 365 Copilot, and Windows Commercial on-premises and Office licensed on-premises.
Cheap or expensive? priced in line with its group
Its price-to-earnings (P/E) is 29.2 versus 35.0 for 4 direct peers — priced in line with its group.
Revenue is growing 18% versus the same quarter last year.
On analysts' next-year forecasts the multiple drops to 25.1 — they expect higher earnings.
The average analyst price target is 601.73, 15% above the current price (their view, not ours).
The stock sits at 87% of its one-year range (0% = the low, 100% = the high).
The risks
- • Quarterly report in 3 days (2026-10-28) — a day the stock can move a lot.
Strengths
- ✅ Profitable — 40 of every 100 dollars of revenue stays as profit.
- ✅ Generates free cash flow — profit becomes cash in the bank.
- ✅ Most analysts rate it buy (54 vs 0).
- ✅ Revenue is growing 18% a year.
- ✅ Pays a dividend (0.7% a year).
What the market is talking about this week
The week centered on whether Microsoft's massive AI infrastructure spending is backed by real demand, ahead of the October 28 earnings report.
- An article naming Microsoft a low-risk pick says fiscal 2026 capital spending, including finance leases, reached $140.6 billion, up 65% in one year. [4]
- AI-boom critic Ed Zitron cited a Bloomberg report that Microsoft has about 2 gigawatts of AI compute online out of 12 gigawatts reported. [1]
- The same critic argued OpenAI and Anthropic have become "load-bearing" customers for Microsoft, and said if they falter, "let them die." [1]
- Press rumors say next-generation consoles from Sony and Microsoft could launch with price tags above $1,000. [6]
- A market preview described a heavy pre-election week, with Alphabet and Amazon results and a Federal Reserve meeting. [3]
A summary of the articles below only, each point with its source. Not a forecast, not a recommendation.
What to watch
- The October 28 earnings report: compare with last quarter ($90B revenue, EPS 4.74 vs 4.21 expected) to see whether the pace held. (2026-10-28)
- What the company says about future capital spending, after a year in which it jumped 65% to $140.6 billion. (2026-10-28) [4]
- How much AI compute is reported as actually online, versus the claim that only about 2 of 12 gigawatts are live. [1]
- Free cash flow: $19.6 billion last quarter versus $35.8 billion net income — the gap shows how much profit is absorbed by investment. (2026-10-28)
What changed this week
Over the past week the stock fell 0.9% (for comparison: S&P 500 -0.4%, sector ETF XLK -0.1%).
This week's news
- AI bear slams Nvidia's GPU pitch: 'There's not scarcity other than that which is created by Jensen Huang' finance.yahoo.com · 2026-10-24
Interview with AI-boom critic Ed Zitron, who claims Nvidia manufactures scarcity, notes Microsoft has ~2GW of AI compute online out of 12GW reported, and calls OpenAI and Anthropic "load-bearing" for Microsoft. source ↗ - Earnings Scoreboard: 82% firms beat EPS estimates, 79% post Y/Y earnings growth seekingalpha.com · 2026-10-24
Earnings-season roundup: of 76 S&P 500 firms reporting, 82% beat EPS estimates; the piece details Tesla, Meta, AT&T, Netflix, GE and IBM, not Microsoft. source ↗ - Stock Market Action Plan: A Preelection Week Primer finance.yahoo.com · 2026-10-24
Short preview of a busy pre-election trading week: results from Alphabet and Amazon, a Fed meeting, and pre-election positioning. source ↗ - Microsoft Stock And 2 Other Best Defensive Stocks finance.yahoo.com · 2026-10-24
A screener article lists Microsoft among three "low risk" stocks thanks to cloud, productivity software and a strong balance sheet, citing fiscal 2026 capex of $140.6 billion, up 65%. source ↗ - Billionaire Paul Tudor Jones warns AI and IPOs could hit stocks hard in 2027. Protect your nest egg now finance.yahoo.com · 2026-10-24
Paul Tudor Jones told CNBC 2027 will be challenging for stocks due to rising share supply from IPOs; Microsoft is mentioned only regarding its 2023 Activision purchase. source ↗ - Sony (TSE:6758) Stock Looks Fairly Valued Following Next Console Price Rumors finance.yahoo.com · 2026-10-24
A valuation analysis of Sony, noting rumors that next-generation consoles from Sony and Microsoft could cost more than $1,000. source ↗
What changed since last week
No material change: same valuation verdict, same risk flags, price moved less than 3%.
A description of facts from the filings and the market — not investment advice or a recommendation. "Cheap" and "expensive" are always relative to the comparison group. Educational information only — not investment advice. Not a registered investment adviser or broker-dealer.