 TechAnalyzer Pro
Meta Platforms Inc. META
Stock research in plain language · As of Oct 25, 2026 · updated once a week, after the trading week closes
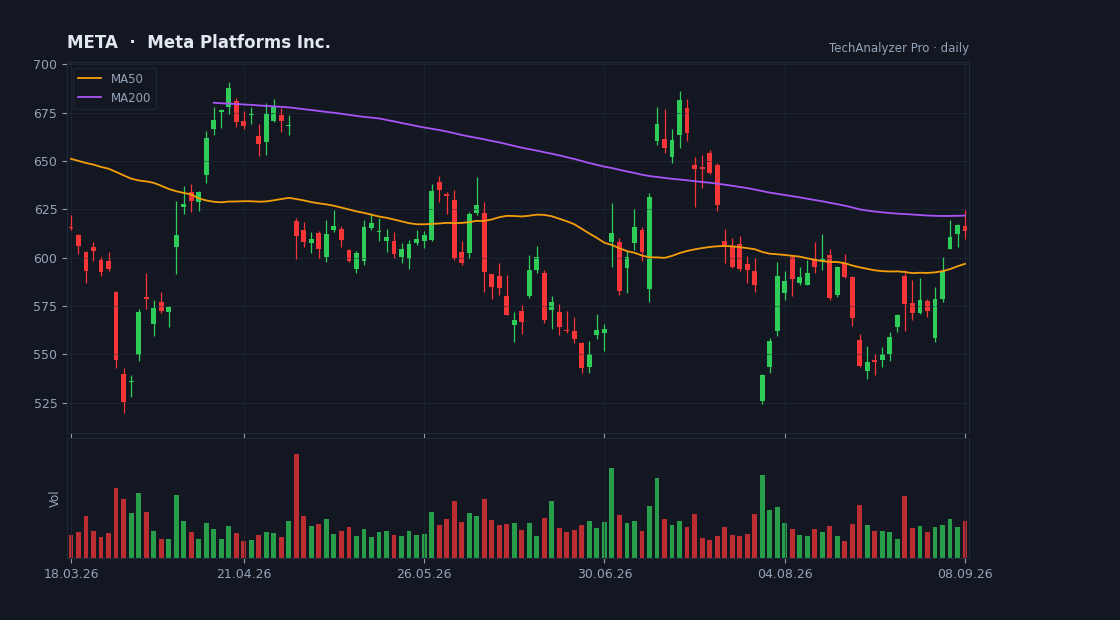
Daily candles, 50 and 200-day averages and volume · updated every trading day · click to open the live chart
The bottom line
Meta moves mainly on two numbers: revenue growth (26% YoY, $64.6B last quarter) versus the scale of AI spending, guided at $135B–$145B for 2026. Last quarter showed $9.86B net income but negative free cash flow of $1.16B, with $82B cash against $112B debt. Its P/E of 22.1 sits below the peer median of 24.6, so the price embeds no special premium, while the average analyst target ($843) is far above the last close ($642.6). The central tension: the advertising core funds enormous outlays that Reality Labs and the AI bet have not yet repaid — and the stock fell 9.4% this week while the broad market barely moved.
An explanation of the mechanics from the facts on this page, not advice.
What the company does
Meta Platforms Inc. is a mega-cap company in the Communication Services sector (Internet Content & Information), with a market value of $1.64T, based in the USA.
It employs about 66,775 people and has been listed since May 18, 2012.
Meta Platforms, Inc. engages in the development of products that enable people to connect and share with friends and family through mobile devices, personal computers, virtual reality (VR) headsets, and AI glasses in the United States, Canada, Europe, Asia-Pacific, and internationally. It operates through two segments, Family of Apps (FoA) and Reality Labs (RL).
Cheap or expensive? priced in line with its group
Its price-to-earnings (P/E) is 22.1 versus 24.6 for 4 direct peers — priced in line with its group.
Revenue is growing 26% versus the same quarter last year.
On analysts' next-year forecasts the multiple rises to 24.6 — they expect lower earnings.
The average analyst price target is 843.39, 31% above the current price (their view, not ours).
The stock sits at 47% of its one-year range (0% = the low, 100% = the high).
The risks
- • More cash leaves than comes in (negative free cash flow).
Strengths
- ✅ Profitable — 15 of every 100 dollars of revenue stays as profit.
- ✅ Most analysts rate it buy (55 vs 1).
- ✅ Revenue is growing 26% a year.
- ✅ Pays a dividend (0.3% a year).
What the market is talking about this week
Strong quarterly revenue alongside huge AI spending and a new share class that preserves Zuckerberg's control.
- Meta reported quarterly revenue of $64.6B, up 26% year over year, and adjusted EPS of $7.40, excluding a $9.89B legal charge. [6]
- The company guided to Q4 revenue of $73B–$76B and 2026 capital spending of $135B–$145B, driven by AI investment. [6]
- Meta will create a new non-voting Class C share from Jan 19, 2027, for raising capital, employee pay and acquisitions, preserving Zuckerberg's control. [5]
- Per the filing, Class C shares are expected to trade at a discount to voting stock and cannot meet tax-deferred deal requirements. [5]
- SLB is opening a Canadian facility to assemble modular components for Meta's data centers, with planned opening in the first half of 2027. [3]
A summary of the articles below only, each point with its source. Not a forecast, not a recommendation.
What to watch
- Whether Q4 revenue lands in the company's guided $73B–$76B range — a direct test of management's own forecast. (Q4 2026) [6]
- The Jan 19, 2027 effective date of the Class C shares and whether they trade at a discount to voting stock, as the company itself flagged. (2027-01-19) [5]
- Free cash flow in the next report: it was negative $1.16B last quarter while AI spending keeps rising.
- Progress at SLB's Canadian facility toward its first-half 2027 opening — an indicator of Meta's data center build pace. (H1 2027) [3]
What changed this week
Over the past week the stock fell 9.4% (for comparison: S&P 500 -0.4%, sector ETF XLC -4.4%).
The company published its quarterly report this week — see the plain-language summary above.
This week's news
- 3 Top Founder Led Stocks To Watch With Up To 82% Revenue Growth finance.yahoo.com · 2026-10-25
A screen of founder-led stocks highlights Meta: Zuckerberg holds ~61% of voting rights, Family of Apps revenue ~$239.4B, Reality Labs ~$2.2B revenue and a $19.19B loss in 2025. source ↗ - Nvidia’s Jensen Huang Says AI Agents Have Sent Token, GPU Demand ‘Through the Roof’: Gene Munster Sees 15 Million Bot Users Soaring to Billions finance.yahoo.com · 2026-10-25
Nvidia's CEO said in Berlin that AI agents, including Meta Muse, sharply raise compute consumption; analysts cited this as support for chip demand. source ↗ - SLB (SLB) Opens Canada Facility After Data Center Win Changed The Story finance.yahoo.com · 2026-10-24
SLB is launching a Canadian facility to assemble and commission modular components for Meta's data centers, with opening planned for the first half of 2027. source ↗ - Why Is CVS Health (CVS) Hiring A Top AI Leader For Pharmacy? finance.yahoo.com · 2026-10-24
CVS appointed Jack Hanlon, previously a senior data executive at Meta and Reddit, as senior VP of AI and analytics for retail and pharmacy. source ↗ - Meta Just Unveiled a New Takeover Weapon — But There's a Catch finance.yahoo.com · 2026-10-24
With Q3 results Meta announced a Class C non-voting share dividend for each existing share, effective Jan 19, 2027; the filing notes an expected price discount and a tax limitation in acquisitions. source ↗ - Earnings Scoreboard: 82% firms beat EPS estimates, 79% post Y/Y earnings growth seekingalpha.com · 2026-10-24
An earnings roundup: Meta reported $64.6B revenue (+26%), adjusted EPS of $7.40 excluding a $9.89B legal charge, Q4 guidance of $73B–$76B and 2026 capex of $135B–$145B. source ↗
What changed since last week
• New risk flag: negative free cash flow.
• Risk flag cleared: earnings report coming up.
• No longer a strength: positive free cash flow.
• The price fell 12.9% since the last summary.
• The average analyst target moved from 805.50 to 843.39.
• A new quarterly report was published (quarter ended Sep 30, 2026).
A description of facts from the filings and the market — not investment advice or a recommendation. "Cheap" and "expensive" are always relative to the comparison group. Educational information only — not investment advice. Not a registered investment adviser or broker-dealer.