 TechAnalyzer Pro
Bloom Energy Corp BE
Stock research in plain language · As of Nov 01, 2026 · updated once a week, after the trading week closes
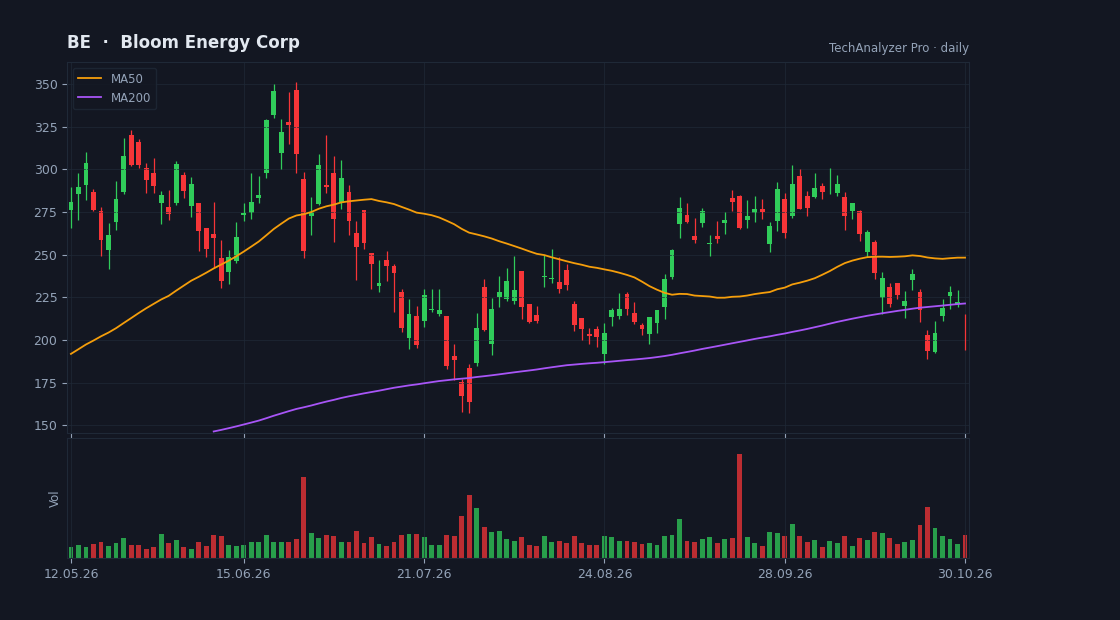
Daily candles, 50 and 200-day averages and volume · updated every trading day · click to open the live chart
The bottom line
This stock moves mainly on delivery pace and guidance: last quarter revenue was $1.236b, up 138% year-over-year, with $250m net income. At the same time free cash flow was negative $181m and share count grew about 38%, so growth is funded by financing and factory investment. A P/E near 123 versus a 27 sector median embeds years of rapid expansion, at a ~$60b market cap. The central tension: strong execution and raised guidance against extreme volatility (beta 3.78, 42% drawdown) and dependence on big-customer project timing.
An explanation of the mechanics from the facts on this page, not advice.
What the company does
Bloom Energy Corp is a large-cap company in the Industrials sector (Electrical Equipment & Parts), with a market value of $60.0B, based in the USA.
It employs about 2,214 people and has been listed since Jul 25, 2018.
Bloom Energy Corporation designs, manufactures, sells, and installs solid oxide fuel cell systems for on-site power generation in the United States and internationally. It offers Bloom Energy Server, an energy server platform to convert fuel, such as natural gas, biogas, hydrogen, or a blend of these fuels, into electricity through a non-combustion electrochemical process. The company also provides Bloom Electrolyzer for producing hydrogen.
Cheap or expensive? relatively expensive
Its price-to-earnings (P/E) is 123.1 versus 27.1 for the median of the Industrials sector in our universe (24 companies) — relatively expensive.
Revenue is growing 138% a year — the market is paying ahead for that growth. If it slows, the high multiple becomes the risk.
On analysts' next-year forecasts the multiple drops to 35.2 — they expect higher earnings.
The average analyst price target is 284.88, 40% above the current price (their view, not ours).
The stock sits at 46% of its one-year range (0% = the low, 100% = the high).
The risks
- • More cash leaves than comes in (negative free cash flow).
- ⚠️ The share count grew 38% in a year — each share owns a smaller slice of the company.
- • The stock is more volatile than average (beta 3.8) — big daily moves both ways.
- • The stock is 42% below its one-year high.
Strengths
- ✅ Profitable — 20 of every 100 dollars of revenue stays as profit.
- ✅ Most analysts rate it buy (15 vs 2).
- ✅ Revenue is growing 138% a year.
What the market is talking about this week
A stronger-than-expected quarter and a raised full-year outlook, against demand for on-site power for data centers.
- Bloom Energy reported third-quarter 2026 revenue of $1.24 billion, above the $1.07 billion consensus, and adjusted earnings of 94 cents per share versus 71 cents expected. [6]
- Management raised 2026 revenue guidance to $4.4-$4.6 billion, roughly 122% year-over-year growth at the midpoint, with adjusted EPS of $3.10-$3.40. [6]
- CFO Simon Edwards cautioned that the timing of several year-end deliveries will determine where within the guidance range the final result lands. [6]
- CEO K. Sridhar said capacity is expanding beyond the 5-gigawatt milestone at Fremont but declined to give timing; quarterly capital spending reached $153 million. [6]
- Bloom was named in several market write-ups as a growth name tied to on-site power demand from data centers, alongside new rules for connecting large electricity loads. [1] [2] [3] [4] [5]
A summary of the articles below only, each point with its source. Not a forecast, not a recommendation.
What to watch
- The fourth-quarter report: whether full-year revenue lands inside the $4.4-$4.6 billion range, which hinges on year-end delivery timing. [6]
- Free cash flow, which was negative $181m last quarter, alongside capital spending that reached $153m in the quarter. [6]
- Updates on the Fremont capacity expansion beyond 5 gigawatts, for which the CEO declined to give a timeline. [6]
- NERC filing its computational-load reliability standards with FERC for approval, which affects how data centers connect to the grid. [5]
What changed this week
Over the past week the stock rose 5.1% (for comparison: S&P 500 -0.6%, sector ETF XLI +1.7%).
This week's news
- Bloom Energy or Plug Power: Which Offers Better Long-Term Upside Now? finance.yahoo.com · 2026-10-30
A comparison piece between Bloom Energy and Plug Power, describing each company's fuel cell technology and demand for reliable on-site power for data centers and hospitals. source ↗ - 3 Growth Stocks With Revenue Growth Up To 31% finance.yahoo.com · 2026-10-30
A growth-stock screen listing Bloom Energy with about $3.83b in revenue and a $67.4b market cap, flagging risk from timing of large customer projects. source ↗ - 3 Growth Stocks To Own In October 2026 finance.yahoo.com · 2026-10-30
Another growth-stock roundup naming Bloom Energy alongside AMD, pointing to an unresolved shift in large-customer buying behavior as the key issue. source ↗ - 3 Growth Stocks With Earnings Growth Up To 66% finance.yahoo.com · 2026-10-29
A third screener article presenting Bloom Energy with roughly $3.8b in sales and a market value of about $64.6b. source ↗ - Natural Gas Is Plentiful. Getting It Into AI Power Is the Hard Part finance.yahoo.com · 2026-10-28
Market commentary on natural gas and AI power: Henry Hub at $2.76, NERC adopted computational-load reliability standards on October 26; Bloom is listed among active companies. source ↗ - Bloom Energy Q3 Earnings Call Highlights Guidance Hike & Capacity Plan finance.yahoo.com · 2026-10-28
Recap of the Q3 earnings call: $1.24b revenue, 94 cents adjusted EPS, full-year guidance raised to $4.4-$4.6b, ~34% adjusted gross margin, and Fremont manufacturing expansion. source ↗
What changed since last week
This is the first summary for this stock; from next week this section shows what changed.
A description of facts from the filings and the market — not investment advice or a recommendation. "Cheap" and "expensive" are always relative to the comparison group. Educational information only — not investment advice. Not a registered investment adviser or broker-dealer.